Two Tree Financial logo

TWO TREE FINANCIAL

Building under construction with a crane icon
Hand holding coins icon
Tax form icon
Folder with magnifying glass icon

Earned is not the same as kept. →

For owners of contingency fee law firms who are done finding out too late.

Request your free Owner’s Paycheck
YOU CANNOT Person losing coins icon OUT-EARN
A BAD STRUCTURE.
SO WE Building under construction with a crane icon REDESIGN
THE STRUCTURE.

Sound familiar?

What contingency firm owners tell us before we work together

If any of these sound like you, you are finding out too late.

Who We Build For

Success has a structural limit.

At a certain point, a growing practice stops having an income problem and starts having a structure problem. Bigger fees, more cases, more entities, and more staff do not automatically create more wealth. Wealth is what you keep. We build for contingency fee firm owners whose practice has outgrown standard tax planning.

Lawyer leaving a firm icon

The solo who left the firm

You went out on your own and the entity was set up by whoever was cheapest that year. The first big fee is coming, and nothing underneath it was designed.

Two partners at one desk icon

The two-partner shop

Two equity partners, a few associates, and income that swings with the docket. The pay, the plan and the estimates were never built for a swing.

Firm building with rising bars icon

The growing firm

More attorneys, more case costs on the books, a line of credit, and a bigger year every year. Complexity arrived before anyone designed for it.
Who we are not for

Saying no to the wrong client is one of the most important things we do for the right one.

We are probably not the right fit if you:

  • Want to put the next big fee into whatever the market is excited about this month.
  • Want to keep running the firm’s finances yourself and have us check your work.
  • Are in your first year out on your own, with no fee in sight to plan around yet.
  • Plan to sell or merge the firm in the next six months.
  • Want an advisor to approve decisions already made rather than design what happens next.

Still here? Then let’s look at your numbers.

Request your Owner’s Paycheck

The cost of passive planning

Compliance is the floor, not the plan.

Most tax plans aren’t built to fail. They’re built to comply. That works for a salary. For a firm that earns in settlements, the big year stacks surtaxes on top of your bracket and phases out deductions you used to get, and a plan that only files correctly lets that drag compound year after year. Here is how quickly the federal rates alone add up.

37%
Top federal income tax bracket.
+3.8%
Net investment income tax, layered on top.
= 40.8%
Top federal rate on investment income, before state tax.
Up to 23.8%
Top federal rate on long-term gains, such as the sale of a business.

Federal rates under the Internal Revenue Code (§1, §1(h), §1411) as of 2026. State taxes not included. Individual results vary.

YOUR TAX STRUCTURE

This is not traditional tax planning

Traditional tax firms are built to file accurately and stay compliant. That matters. But for the owner of a contingency fee firm, filing correctly is not the same thing as keeping the fee.

Two Tree Financial is a tax-first wealth architecture firm. We find where the firm’s structure leaks, redesign it before the next fee lands, coordinate the moving parts of your financial life, and invest what you keep with discipline.

TopicTwo Tree FinancialTraditional Tax Firm
PerspectiveDesigns what happens nextFiles what already happened
MethodRedesigns the structureFiles around the structure
PricePriced to the opportunityPriced as a commodity
StandardProactive and defensibleCorrect and compliant
Wealth meansWhat you keepWhat gets reported
CoordinationOne coherent systemTaxes handled in isolation
InvestingEvidence-based, once the structure is setReferred out to someone else
OutcomeRetained wealthAn accurate return

We cut through the noise to the levers that matter.

We believe inclarity over complexity

  • Clarity over Complexity

    If advice creates more confusion, it is not doing its job. We build for clarity first.

  • Coordination over Fragmentation

    Taxes, retirement planning, and investments should work together, not live in separate silos.

  • Leverage over Activity

    We focus on the moves that materially improve outcomes, not the ones that merely create motion.

How it works

From your returns to a structure built to last

  1. 01

    The Owner’s Paycheck Free

    Start with a 20-minute Kickoff call, then share two years of returns and a balance sheet. We measure what the firm earned, what actually reached you, and where your structure leaks, in dollars, with your last three years side by side, and deliver it on your own private page.

    What happens
    • Review two years of personal and firm returns and your entity setup.
    • Measure what the firm earned and how much of it reached you.
    • Identify where tax drag and fragmentation cost you most, in dollar ranges.
    • Benchmark your current structure against today’s tax rules.
    The gap, in dollarsA clear view of what is being left on the table.
    Outcomes scorecardWhere your current setup is strong, weak, or outdated.
  2. 02

    The Vision Conversation

    We agree on where you are going: a practice that is tax-efficient, an investment strategy that lets you sleep, and a life not run by financial news.

    What happens
    • What a fully tax-efficient practice would look like for you.
    • What kind of investment strategy you can live with through any market.
    • What life you want your wealth to support, and on what timeline.
    An agreed destinationThe Blueprint is built around where you are going, not just this year’s return.
  3. 03

    The Architectural Blueprint

    Your complete plan across entities, cash flow, retirement, investments, risk, and estate, with the order to put it in place.

    What happens
    • Design the firm entity, partner pay, and ownership structure for efficiency.
    • Evaluate retirement plan design for a small owner group, including cash balance plans.
    • Plan the fee year before the fee lands: timing, entity choices, and planning vehicles.
    • Prioritize the few structural changes with the highest impact.
    Tax architectureA structure designed to reduce drag before it compounds.
    Maximum leverageMore impact from fewer, better decisions.
  4. 04

    Implementation and ongoing coordination

    We put the plan in place, coordinate every moving part, and keep it current year over year.

    What happens
    • Coordinate every moving part, from entities to filing, so nothing falls between advisors.
    • Make sure new entities, trusts, and accounts are set up properly.
    • Layer in disciplined, evidence-based investing.
    • Review the structure as fees, laws, and life change, and prepare for the big year and the eventual sale early.
    A unified systemTaxes, planning, and investments working together.
    Long-term disciplineA strategy built to hold through markets, growth, and transition.

Discipline, not drama, at every step.

How we charge

  • The Owner’s Paycheck is free.
  • The Architectural Blueprint is a one-time fee, set in writing before you sign and shown next to what the Owner’s Paycheck found.
  • Ongoing work is priced by complexity: how many entities and states your structure involves. The fee is computed and shown to you, never negotiated.
  • We are paid only by our clients. No commissions.
  • If the numbers don’t justify the engagement, we’ll tell you.
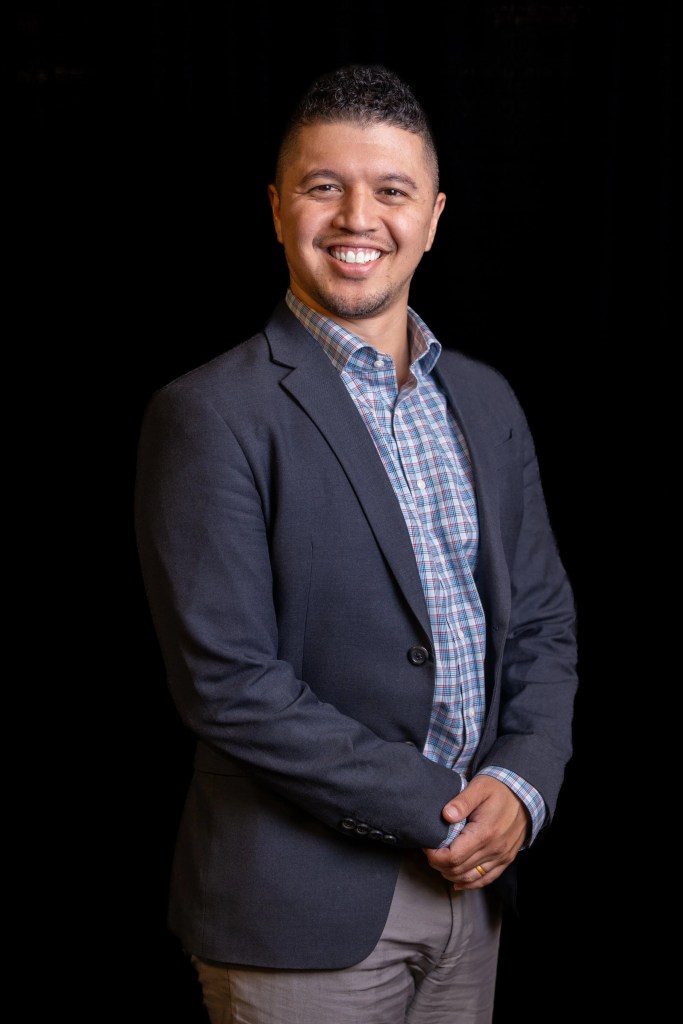
Brian Duerson, founder of Two Tree Financial

Brian Duerson, MSF

Founder and Financial Architect

Most financial advice is built for the wrong problem. In a firm that earns in settlements, the big year pushes you past the 32 percent bracket, deductions phase out, surtaxes switch on, and the pieces of your financial life, a CPA, an advisor, a retirement plan, rarely work together. You find out in April.

I built Two Tree Financial to fix that in the right order. Most people in my industry are financial repairmen who patch the mess you already have. I work as a financial architect: I redesign the tax structure first, then build a disciplined, evidence-based investment strategy on top of it.

I have worked in financial services since 2018, as a trader, in operations at a fintech company, and as a financial planner, and I hold a Master of Science in Finance from Johns Hopkins. My deepest client relationship today is a two-attorney household running six entities, and I built the firm around what that work taught me. In every one of those seats I saw the same thing: successful people rarely need more information. They need judgment, and the right decisions in the right order.

Deep roots. Quiet shade.

  • Johns Hopkins University

    Johns Hopkins

    M.S. in Finance

  • Logos of firms Brian previously worked with

    Since 2018

    In finance and fintech

  • Brian with his wife and three sons

    Family

    Husband and father of three

  • Faith

    Faith

    Anchored by Christ

Logos are trademarks of their respective owners. No affiliation or endorsement is implied.

A fiduciary, paid only by our clients. Two Tree Financial is a state-registered investment adviser and a fiduciary, which means we are required to act in your best interest. Verify our registration (CRD# 331906)

Nationwide, virtually. We are registered in South Carolina and Utah, and in other states we can work with a limited number of clients under each state’s rules. We are not accepting new clients in California at this time.

Frequently asked questions

Two Tree Financial operates outside the traditional financial services model. Because our Architecture-first approach is unique to the industry, questions are expected. If you’re ready to look beneath the surface of your current structure, let’s start a conversation.